WACC Formula Explained: Calculation and Worked Example
The weighted average cost of capital, or WACC, is the blended return a company must offer the investors who finance it. The formula looks compact, but a reliable calculation depends on choices that the formula does not make for you: market values instead of book values, a defensible cost of equity, a current cost of debt, the right tax rate, and consistent treatment of currency and inflation.
This guide explains the WACC formula from the ground up and then calculates it for a hypothetical North American company. You’ll learn how to estimate each input, use WACC in a discounted cash flow model, adapt the method for private companies and individual projects, and recognize cases where a single company-wide rate is misleading. A final checklist turns the theory into a repeatable process you can use in Excel, valuation work, capital budgeting, or finance interviews.
What Is WACC?
WACC is a company’s weighted average required return across debt, common equity, and any other long-term capital. Each funding source is weighted by its share of the company’s market-value capital structure. Because interest may reduce taxable income, debt normally enters the calculation at its after-tax cost.
Think of a company as a portfolio funded by different investors. Lenders expect interest and principal repayment. Common shareholders expect dividends and capital appreciation. Preferred shareholders may expect a fixed dividend. WACC combines those required returns into one percentage that reflects how the business is financed.
WACC is a forward-looking opportunity cost, not simply the interest rate shown on the income statement. If a business has a WACC of 8.5%, the interpretation is that its capital providers collectively require about an 8.5% expected annual return on the capital they have supplied, given the estimated risk and financing mix.
That does not mean the company writes an 8.5% check each year. Part of the required return belongs to shareholders and may arrive through future growth in value rather than a cash payment. WACC is therefore an economic cost of capital, not an accounting expense.
The WACC Formula and What Each Term Means
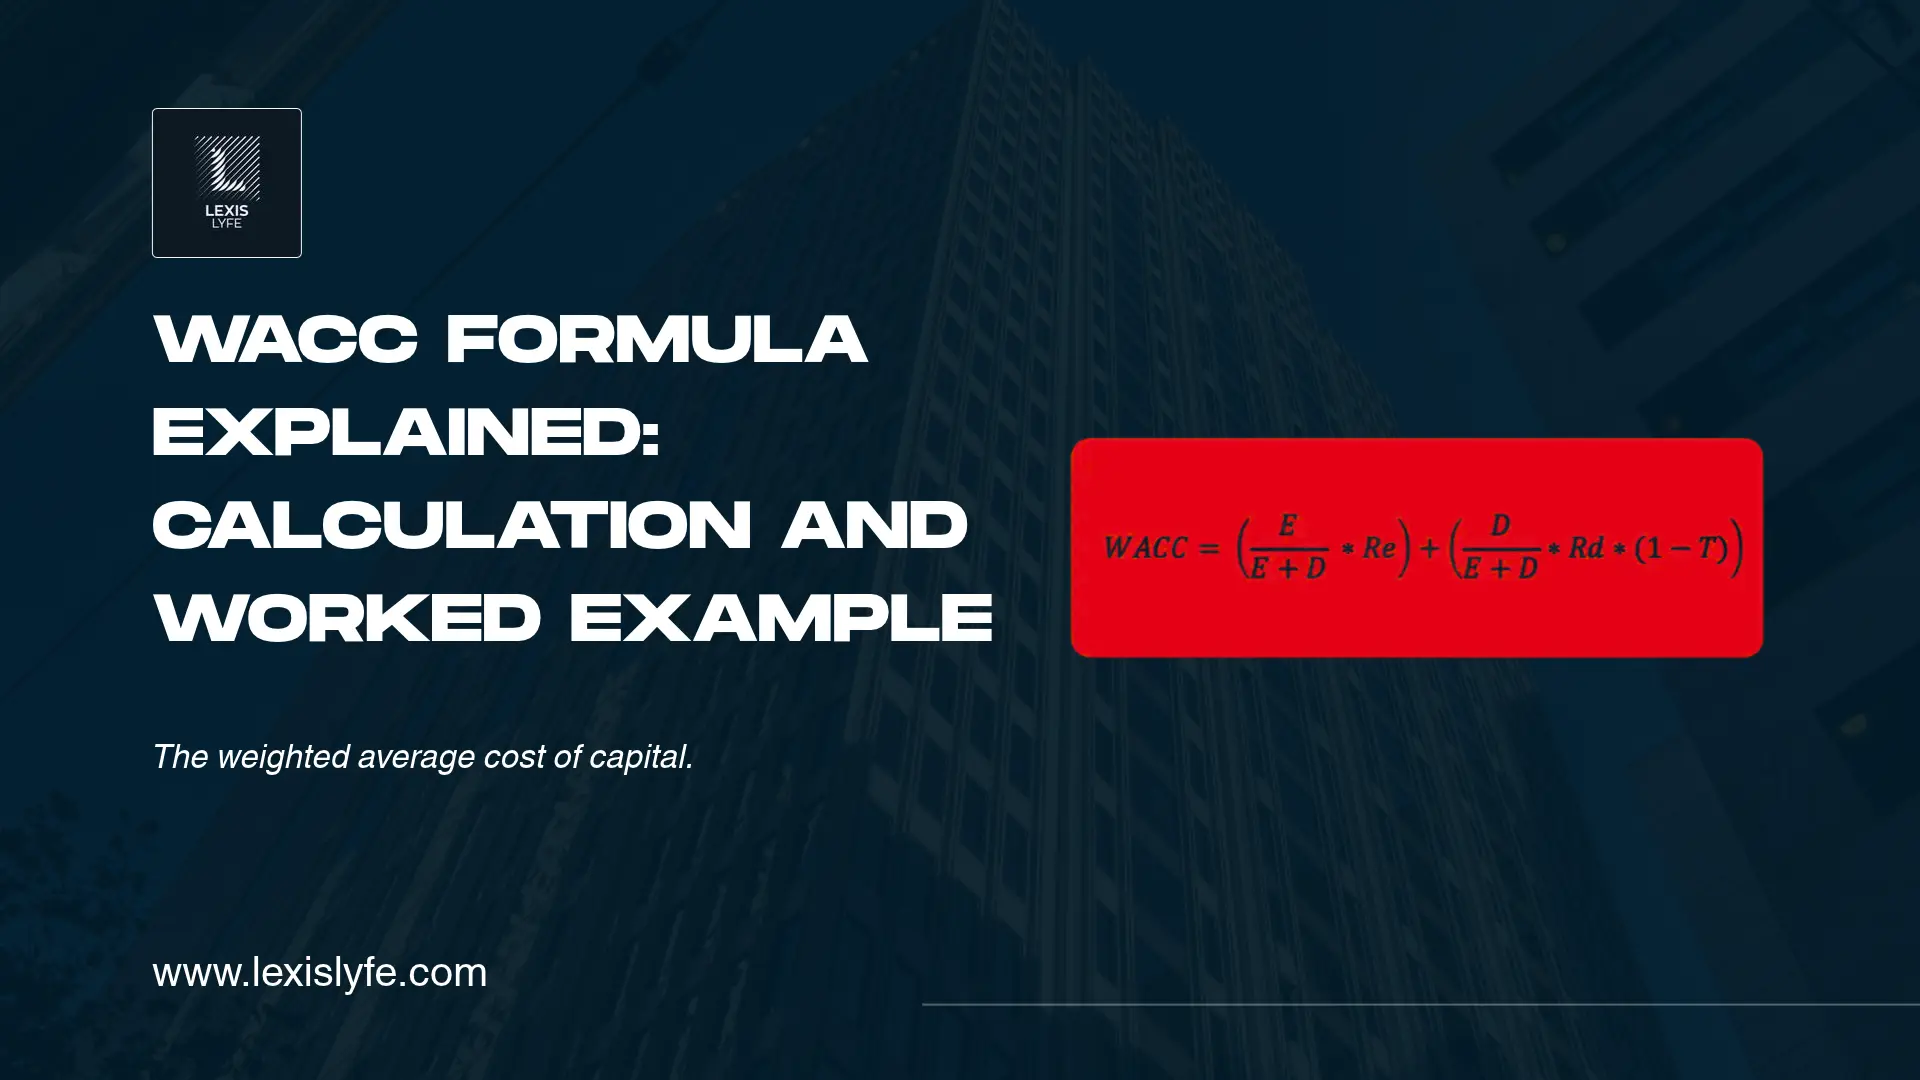
For a company funded only with common equity and interest-bearing debt, the standard formula is:
$$
\text{WACC}=\left(\frac{E}{D+E}\times R_e\right)+\left(\frac{D}{D+E}\times R_d\times(1-T)\right)
$$| Symbol | Meaning | Preferred measurement |
|---|---|---|
| $E$ | Market value of common equity | Share price × diluted shares outstanding |
| $D$ | Market value of interest-bearing debt | Traded price of debt, or a reasonable market-value estimate |
| $V$ | Total invested capital, normally $D+E$ | Sum of included capital sources |
| $R_e$ | Cost of common equity | Often estimated with CAPM |
| $R_d$ | Pre-tax cost of debt | Current yield to maturity or current borrowing rate |
| $T$ | Marginal corporate tax rate | Expected rate applicable to incremental interest deductions |
The equity weight is $E/V$, and the debt weight is $D/V$. Those weights must add to 100%. If preferred stock is material, extend the formula:
$$
\text{WACC}=w_eR_e+w_dR_d(1-T)+w_pR_p
$$
Here, $w_p$ is preferred stock’s market-value weight and $R_p$ is its required return. Preferred dividends generally do not receive the same corporate tax deduction as interest, so the debt tax adjustment is not automatically applied to preferred stock.
Why debt is multiplied by one minus the tax rate
Interest expense can reduce taxable income when the deduction is usable and not restricted. If a company pays 6% interest and receives a full tax benefit at a 25% marginal rate, its simplified after-tax debt cost is:
$$
6.0%\times(1-25%)=4.5%
$$
The adjustment recognizes the interest tax shield. It should not be applied mechanically when a firm cannot currently use the deduction, has persistent tax losses, faces interest-deduction limits, or operates across jurisdictions with different tax treatment. In those cases, model the expected cash tax benefit explicitly or use a more supportable effective marginal rate.
Why market values usually replace book values
WACC represents the return required by today’s capital providers, so the weights should reflect current economic values. A stock issued years ago at $10 but trading at $40 is not economically financed at the historical book amount. The same logic applies to fixed-rate debt whose value changes when market yields or credit risk change.
Book debt may serve as an approximation when the debt is recently issued, floating-rate, or close to par. Book equity is usually a poor substitute for market equity because retained earnings and accounting conventions do not represent what shareholders’ claims are worth today.
How to Calculate WACC in Six Steps
Calculate WACC by defining the valuation context, estimating market-value capital weights, finding the current costs of equity and debt, applying the usable tax shield, and summing the weighted components. Finish by testing the result against peers and checking that it matches the cash flow’s currency, inflation basis, and risk.
Step 1: Define what you are valuing
State the company, valuation date, currency, and cash flow being discounted. This step prevents many hidden errors.
- Company or project: whole operating business, division, acquisition, or standalone project
- Valuation date: the date on which market inputs are observed
- Currency: U.S. dollars, Canadian dollars, or another currency
- Cash flow: nominal or real; pre-tax or after-tax; FCFF or FCFE
WACC is normally paired with after-tax free cash flow to the firm, also called FCFF or unlevered free cash flow. FCFF belongs to debt and equity investors before financing payments. Free cash flow to equity belongs only to common shareholders and should generally be discounted at the cost of equity, not WACC.
Step 2: Estimate the market value of each capital source
For a public company, market equity equals the current share price multiplied by diluted shares outstanding. Use a consistent valuation date. If the share price is highly volatile, disclose whether you used the spot price or a short averaging period.
Debt requires more judgment. For traded bonds, use quoted market prices. For non-traded borrowings, estimate market value by discounting promised payments at a current rate for debt with similar maturity and credit risk. If the difference from book value is unlikely to be material, book debt can be a documented shortcut.
Decide whether lease liabilities, preferred stock, convertible securities, non-controlling interests, or other claims belong in the capital base. Treatment should match the cash flow and enterprise-value bridge. Counting a liability in WACC while also deducting it elsewhere without consistent cash-flow treatment can create double counting.
Step 3: Estimate the cost of equity
The cost of equity is the return common shareholders require for bearing business and financial risk. It is not directly observable. The capital asset pricing model, or CAPM, is the most common starting point:
$$
R_e=R_f+\beta_L\times ERP
$$
$R_f$ is the risk-free rate, $\beta_L$ is levered equity beta, and $ERP$ is the equity risk premium. Depending on the company and market, the estimate may also include a country risk premium or size premium.
Step 4: Estimate the current pre-tax cost of debt
The cost of debt should reflect what the company would pay to borrow now, not simply the average coupon on debt issued in the past. Use the yield to maturity on traded debt when available. If it is not, add a credit spread appropriate for the company’s rating and maturity to a same-currency risk-free benchmark.
For a private or unrated company, possible evidence includes recent loan proposals, the rate on a recently negotiated facility, a synthetic credit rating based on interest coverage, or the yields of comparable issuers. Avoid using a bank’s base rate without adding the borrower-specific spread.
Step 5: Apply the appropriate tax adjustment
Use the marginal tax rate expected to apply to incremental deductible interest, not automatically the historical cash tax rate. A U.S. corporation may start with the 21% federal corporate rate documented by the IRS, then consider state taxes and deduction interactions. A Canadian corporation normally requires the relevant federal and provincial or territorial rate, with attention to business type and available reductions.
Historical effective tax rates can be distorted by tax credits, loss carryforwards, one-time items, foreign income, valuation allowances, and changes in deferred taxes. If the company cannot use the interest deduction soon, a full immediate tax shield overstates debt’s benefit.
Step 6: Weight, add, and sanity-check the components
Multiply each required return by its market-value weight. Apply $(1-T)$ to qualifying debt, then add the results.
Do not stop when the spreadsheet produces a number. Compare the result with the company’s history, comparable firms, industry economics, and current market conditions. Confirm that a riskier business does not inexplicably have a lower discount rate than a stable peer unless the capital structure or another documented input explains it.
WACC Worked Example
Assume Northstar Components is a hypothetical U.S.-based manufacturer valued on October 15, 2026. It has common equity and term debt but no preferred stock. The example uses rounded, illustrative assumptions rather than claiming to reproduce a real company’s market data.
Input assumptions
| Input | Assumption | Basis |
|---|---|---|
| Market value of equity | $600 million | Share price × diluted shares |
| Market value of debt | $400 million | Estimated current market value |
| Risk-free rate | 4.5% | Same-currency, long-term government benchmark, rounded |
| Levered beta | 1.10 | Normalized peer-based estimate |
| Equity risk premium | 5.0% | Illustrative forward-looking market premium |
| Pre-tax cost of debt | 6.0% | Current borrowing/yield estimate |
| Marginal tax rate | 25.0% | Illustrative combined rate |
Total capital is:
$$
V=E+D=$600m+$400m=$1{,}000m
$$
The equity and debt weights are:
$$
w_e=\frac{600}{1{,}000}=60%
$$

$$
w_d=\frac{400}{1{,}000}=40%
$$
Calculate the cost of equity
Using CAPM:
$$
R_e=4.5%+(1.10\times5.0%)=10.0%
$$
Northstar’s estimated cost of equity is 10.0%.
Calculate the after-tax cost of debt
$$
R_d(1-T)=6.0%\times(1-25.0%)=4.5%
$$
The simplified after-tax cost of debt is 4.5%.
Combine the weighted components
| Component | Weight | Required return | Tax adjustment | Contribution to WACC |
|---|---|---|---|---|
| Common equity | 60% | 10.0% | None | 6.00% |
| Debt | 40% | 6.0% | × 75% | 1.80% |
| Total | 100% | 7.80% |
The final calculation is:
$$
\text{WACC}=(60%\times10.0%)+(40%\times6.0%\times75%)=7.8%
$$
A 7.8% WACC means that Northstar’s investors collectively require an estimated 7.8% annual return on the market value of capital committed to the operating business. In a standard enterprise DCF, 7.8% could be used to discount nominal U.S.-dollar FCFF if the forecast carries risk consistent with the business used to estimate the rate.
Check the arithmetic another way
For every $1,000 of market-value capital, the company is treated as having $600 of equity and $400 of debt. Equity investors require $60 per year in expected return: $600 × 10%. Lenders require $24 before tax: $400 × 6%. At a 25% tax rate, the assumed tax shield is $6, leaving a net debt cost of $18. The total required return is $78, or 7.8% of $1,000.
That dollar check makes the weighted-average logic easier to audit and catches percentage-formatting errors in spreadsheets.
How to Estimate the Cost of Equity With CAPM
CAPM estimates the cost of equity as a risk-free return plus compensation for exposure to broad market risk. The calculation is simple, but the valuation can move materially depending on how the analyst selects the risk-free rate, beta, and equity risk premium.
Select a risk-free rate that matches the cash flow
Use a default-free government rate in the same currency as the forecast, with a maturity that reasonably reflects the duration of the cash flows. U.S.-dollar nominal cash flows commonly use a U.S. Treasury yield. Canadian-dollar nominal cash flows commonly use a Government of Canada bond yield.
The company’s headquarters do not determine the currency of the discount rate. A Canadian company valued using U.S.-dollar cash flows needs a U.S.-dollar rate framework. Mixing a Canadian-dollar risk-free rate with U.S.-dollar cash flows embeds inconsistent expected inflation and currency risk.
Record the observation date and exact maturity. The U.S. Treasury publishes daily par yield curve rates, so analysts can use a dated, verifiable source rather than a remembered market number.
Choose an equity risk premium
The equity risk premium is the extra return investors require from a diversified equity market over a risk-free asset. Analysts use historical premiums, forward-looking implied premiums, surveys, or a consistent house assumption.
Whichever method you choose, document it. Aswath Damodaran’s public datasets are a widely used reference for implied U.S. and country risk premiums, with dated updates and stated methodology. Do not combine a historical arithmetic premium from one framework with other inputs calibrated to a different forward-looking framework without explaining the choice.
For a multinational business, distinguish market exposure from incorporation. Country risk may be linked to where revenue, assets, cash flows, and political risks arise. Adding a country premium both to the market ERP and separately elsewhere can double count the same risk.
Estimate beta from the company or comparable firms
Beta measures the sensitivity of equity returns to broad market movements. A beta of 1.0 indicates market-like systematic risk in the model. Above 1.0 implies greater sensitivity; below 1.0 implies lower sensitivity.
Raw regression beta is observable for a listed stock, but it can be noisy because results depend on the market index, return interval, lookback period, trading liquidity, and unusual events. A peer-based beta is often more stable:
- Select comparable public companies with similar operating risk.
- Collect their levered equity betas.
- Unlever each beta to remove the effect of its financing mix.
- Use the median or another robust central measure.
- Relever the peer beta at the subject company’s target debt-to-equity ratio.
The common simplified unlevering equation is:
$$
\beta_U=\frac{\beta_L}{1+(1-T)\times D/E}
$$
Relever it as:
$$
\beta_L=\beta_U\times[1+(1-T)\times D/E]
$$
These equations assume debt beta is approximately zero. That shortcut may be weak for distressed or heavily indebted businesses. More advanced models can recognize risky debt explicitly.
Decide whether additional premiums are justified
Private-company valuations sometimes add a size premium or company-specific risk premium. These adjustments should not become a container for every concern in the forecast. If customer concentration, execution risk, or margin pressure is already reflected through probability-weighted cash flows, adding a large premium for the same issue can double count risk.
A sound practice is to separate systematic risks that belong in the discount rate from diversifiable or scenario-specific risks better modeled in cash flows. Document the empirical source, date, and rationale for every added premium.
How to Estimate the Cost of Debt
The cost of debt is the current return lenders require on the company’s interest-bearing obligations. Use a marginal borrowing cost whenever possible because WACC is forward-looking. Historical interest expense divided by average debt can be a diagnostic, but it is not automatically the correct valuation input.
Publicly traded debt
For a plain-vanilla bond trading in an active market, yield to maturity is usually more informative than the coupon rate. The coupon was fixed when the bond was issued. Yield responds to current risk-free rates, credit spreads, price, and time to maturity.
If the company has several material debt instruments, calculate a market-value-weighted yield across them. Match the selected debt maturity to the long-term financing being modeled and investigate instruments with unusual security, guarantees, convertibility, or subordination.
Non-traded or private debt
When no traded yield exists, common approaches include:
- Recent loan pricing or refinancing proposals
- A risk-free benchmark plus a spread based on the firm’s credit rating
- A synthetic rating inferred from interest coverage and business risk
- Observable yields on comparable borrowers
- A bank-provided borrowing rate adjusted for fees and maturity
Commitment fees, original issue discounts, and material financing costs may affect the economic borrowing cost. A revolver that is undrawn today may still matter to liquidity analysis, but its full commitment should not automatically be treated as funded debt in the capital weight.
Debt tax shield limits
The standard formula assumes the tax shield is available and proportional to interest. Reality can differ. Loss carryforwards may delay the benefit. Tax rules may cap deductible net interest. Multinational groups may incur interest in one jurisdiction while earning taxable income in another. A distressed company may not survive long enough to use future deductions.
When these effects are material, forecast cash taxes explicitly and consider an adjusted present value model. APV values the unlevered business first and then separately adds financing effects such as the present value of usable tax shields.
How to Choose Capital Structure Weights
Capital weights should reflect the financing mix expected over the life of the valued cash flows. Current market values are a strong starting point, but a target capital structure may be better when management actively plans to change debt levels or when the current mix is temporary.
Current versus target capital structure
Use current market weights when the company’s financing is stable and representative. Consider target weights when:
- A recent acquisition temporarily increased debt
- Management has a credible deleveraging or recapitalization policy
- The company is emerging from financial distress
- The subject is private and lacks a market equity value
- A project will be financed in line with a long-run policy
A target should be supported by management policy, credit-rating objectives, mature peer capital structures, debt covenants, and the economics of the business. It should not be chosen merely because it creates a preferred valuation.
Gross debt or net debt
Standard WACC presentations use interest-bearing debt and equity weights. Some practitioners use net debt after subtracting excess cash. The correct treatment depends on the valuation architecture.
If operating cash flows exclude income from excess cash and the DCF produces enterprise value, excess cash is normally added later in the bridge to equity value. Using net debt in the WACC weights can sometimes be a practical convention, but it must be applied consistently and can behave poorly when a company has net cash. State the convention clearly and test whether it produces economically sensible weights.
Circularity between value and weights
Market equity is observable for a listed firm, but a private company’s equity value may be the output of the DCF. That creates circularity: WACC depends on equity value, while equity value depends on WACC.
Possible solutions include using a peer-based target debt-to-equity ratio, iterating the spreadsheet until the capital structure converges, or valuing financing effects separately with APV. Do not silently use book equity merely to avoid circularity.
Preferred Stock, Leases, and Hybrid Capital
Material capital sources should be included when their claims and required returns are distinct. Preferred stock normally receives its own weight and cost. Leases and convertible or hybrid securities require consistent treatment across cash flow, enterprise value, debt, and the discount rate.
Preferred stock
For perpetual preferred stock with a stable dividend, a simplified cost is:
$$
R_p=\frac{D_p}{P_p}
$$
$D_p$ is the annual preferred dividend and $P_p$ is the current net market price. Preferred stock is weighted by market value. If it is callable, convertible, cumulative, or finite-lived, a yield-based calculation may better capture its economics.
Operating leases
Modern accounting places many lease liabilities on the balance sheet, but valuation models still differ in presentation. One consistent method treats leases as debt: include lease liabilities in capital, treat the relevant lease cost as financing, and adjust operating cash flow and enterprise-value reconciliation accordingly.
Another method leaves lease expense in operating costs and excludes lease liabilities from debt. Either method can work if it is internally consistent. Mixing them, such as adding lease liabilities to debt while leaving all lease expense in operating cash flow and deducting the liability again, distorts value.
Convertible and hybrid securities
A convertible bond contains debt and equity-like features. A simple classification based only on its accounting label may miss the economics. Material instruments may need to be decomposed, valued with an option-aware method, or treated consistently through a scenario analysis.
For routine screening, analysts sometimes classify an instrument according to its dominant economic characteristics. For a transaction opinion, purchase price allocation, or audited valuation, obtain specialist advice if the hybrid is material.
How WACC Is Used in Valuation and Capital Budgeting
WACC is most commonly used to discount after-tax FCFF in an enterprise DCF. It also serves as a benchmark for project returns, acquisitions, and capital allocation. The central rule is that the discount rate must match the cash flow’s claimholders, currency, inflation, duration, and risk.
Discounting free cash flow to the firm
Enterprise value can be expressed as the present value of forecast FCFF plus terminal value:
$$
EV=\sum_{t=1}^{n}\frac{FCFF_t}{(1+WACC)^t}+\frac{TV_n}{(1+WACC)^n}
$$
FCFF is before interest and after operating taxes, so it belongs to both debt and equity providers. That makes WACC the conceptually matched rate. After calculating enterprise value, adjust for debt, excess cash, and other non-operating claims or assets to reach common equity value.
Evaluating a project
A project creates value when the present value of its expected cash inflows exceeds its investment cost. Its internal rate of return exceeding an appropriate risk-adjusted hurdle rate is supportive, but NPV is generally the stronger decision measure because it shows value created in dollars.
The company-wide WACC is suitable only when the project has risk similar to the existing business and is financed consistently with the target capital structure. A regulated utility should not use its low corporate WACC unchanged for a speculative software venture. A risky project deserves a project-specific rate or explicit scenario modeling.
Assessing acquisitions
For an acquisition, the target’s operating risk and sustainable financing matter more than the buyer’s convenience. Discounting a risky target at a large acquirer’s lower WACC can overstate value. Synergies should be modeled as incremental cash flows with their own execution risk, not assumed to justify a lower discount rate.
Deal financing also should not be confused with operating value. A buyer may fund a transaction with cheap debt, but more borrowing can increase financial risk and the cost of equity. The blended outcome requires a consistent post-deal capital structure and cash-flow forecast.
The Consistency Triangle: Cash Flow, Currency, and Inflation
A defensible WACC model must pass three linked tests: the rate must match who receives the cash flow, the currency in which the cash flow is stated, and whether the forecast is nominal or real. This consistency triangle is more useful than debating a tenth of a percentage point while mixing incompatible inputs.
| Dimension | Cash-flow choice | Matching discount rate |
|---|---|---|
| Claimholder | FCFF, available to debt and equity | WACC |
| Claimholder | FCFE, available to common equity | Cost of equity |
| Currency | U.S.-dollar cash flow | U.S.-dollar rate framework |
| Currency | Canadian-dollar cash flow | Canadian-dollar rate framework |
| Inflation | Nominal cash flow with price inflation | Nominal discount rate |
| Inflation | Real cash flow excluding inflation | Real discount rate |
Nominal versus real WACC
A nominal rate includes expected inflation; a real rate excludes it. Convert between them using the Fisher relationship:
$$
1+R_{nominal}=(1+R_{real})(1+\pi)
$$
where $\pi$ is expected inflation. Simply subtracting inflation is an approximation. If a forecast grows revenue and costs in nominal dollars, discount it with a nominal rate. If the forecast is expressed in constant purchasing-power terms, use a real rate.
U.S. and Canadian tax considerations
The United States applies a 21% federal corporate income tax rate to ordinary C corporations, according to IRS guidance, but state taxes and interest-deduction rules can change the usable marginal shield. Canada’s federal corporate calculation includes a general tax reduction and may combine with provincial or territorial rates; Canadian-controlled private corporations may qualify for different treatment.
The practical lesson is not to paste 21% or a Canadian headline rate into every model. Identify the legal entity earning the income, the jurisdiction where interest is deducted, expected taxable income, and the rate applying to incremental deductions.
How WACC Affects DCF Value
WACC often has an outsized effect on DCF value because it discounts every forecast cash flow and is usually embedded in terminal value. A small rate change can produce a large valuation change, especially for long-duration businesses whose value depends heavily on distant cash flows.
Suppose Northstar’s year-five FCFF is $80 million and its perpetual growth assumption is 2.5%. The Gordon growth terminal value at a 7.8% WACC is:
$$
TV=\frac{80\times(1+2.5%)}{7.8%-2.5%}=$1{,}547m
$$
At an 8.8% WACC, holding all else constant:
$$
TV=\frac{80\times(1+2.5%)}{8.8%-2.5%}=$1{,}302m
$$
The undiscounted terminal value falls by about 16%. The effect on present enterprise value depends on forecast timing and other cash flows, but the direction is clear.
Build a two-variable sensitivity table
Every serious DCF should show value across a range of WACC and terminal-growth assumptions. Use a range broad enough to reflect estimation uncertainty, often in 0.5-percentage-point increments around the base case, and ensure $WACC>g$ in a perpetual-growth model.
Sensitivity tables do not fix poor assumptions. They reveal how dependent the conclusion is on them. If a transaction works only at the lowest WACC and highest growth combination, the model is signaling fragility rather than confidence.
Avoid false precision
A displayed result of 7.83% can create an illusion of accuracy. Beta, ERP, credit spreads, tax utilization, and target debt levels are estimates. Reporting a reasonable range, such as 7.5% to 8.5%, may be more honest than defending two decimal places.
Use the midpoint for the base case only after explaining the range and its valuation effect. The decision should survive plausible inputs, not depend on cosmetic precision.
How to Interpret WACC
A lower WACC means a company can finance its operations at a lower estimated required return, all else equal. A higher WACC indicates greater operating, financial, market, or country risk. No universal percentage is “good” because industries, currencies, maturities, and market conditions differ.
Compare WACC with:
- The expected return on a project or acquisition
- Return on invested capital, or ROIC
- The firm’s historical WACC calculated on a consistent basis
- Comparable companies using the same methodology and valuation date
- Current government yields, credit spreads, and equity risk conditions
If sustainable ROIC exceeds WACC, the business is generally creating economic value on incremental invested capital. If ROIC remains below WACC, growth can destroy value because each new dollar invested earns less than its opportunity cost.
That comparison requires compatible definitions. Use after-tax operating profit and invested capital consistently for ROIC. Do not compare a pre-tax project return with an after-tax WACC or an accounting return with a market-based hurdle without reconciliation.
WACC vs. Cost of Equity vs. Hurdle Rate
WACC is the blended required return for all long-term capital providers. Cost of equity is the return required only by common shareholders. A hurdle rate is a decision threshold set for a particular investment and may equal WACC, exceed it for added risk, or reflect strategic and capital constraints.
| Measure | Applies to | Typical use |
|---|---|---|
| WACC | Debt and equity capital | Discount FCFF; assess enterprise investments |
| Cost of equity | Common shareholders | Discount FCFE or dividends |
| Cost of debt | Lenders | Price borrowing; calculate WACC component |
| Hurdle rate | Specific project or decision | Approve or reject capital spending |
| Required rate of return | Investor or asset | General return threshold based on risk |
A project hurdle rate should not be reduced merely because management wants more projects approved. Nor should every small operational investment receive an arbitrary premium over WACC. Link the adjustment to project risk, option value, capital scarcity, or forecast bias and document the policy.
Private-Company WACC
A private company lacks an observable share price and often has no traded debt, so analysts build WACC from public-market reference points. The preferred approach uses comparable-company operating risk, a target capital structure, current market rates, and company-specific evidence that avoids double counting.
A practical private-company workflow
- Select comparable public companies based on products, customers, margins, cyclicality, geography, and scale.
- Calculate or source their market debt and equity values.
- Unlever each peer beta using a consistent tax convention.
- Use a median unlevered beta and relever it at the private company’s supportable target debt-to-equity ratio.
- Estimate the cost of debt from recent loan terms, a synthetic rating, or comparable yields.
- Use the marginal tax rate and adjust for whether deductions are usable.
- Add preferred or hybrid capital if material.
- Calculate a range and test it against transaction evidence and industry returns.
Avoid adding a “private-company premium” merely because shares are not publicly traded. Lack of marketability affects the value and liquidity of the ownership interest and may be addressed separately depending on the valuation standard. It is not automatically part of enterprise WACC.
Small-company and concentration risks need thoughtful treatment. Some may influence systematic risk or financing cost. Others belong in scenarios, margins, customer-retention assumptions, or a separate valuation adjustment. The model should show where each risk appears once.
Project-Specific WACC
Project-specific WACC adjusts the discount rate when a project’s operating risk or financing differs materially from the existing company. Estimate it using comparable pure-play businesses or assets, unlever their betas, then relever at a supportable financing mix for the project.
Consider a mature food manufacturer entering early-stage biotechnology. The manufacturer’s historical beta and low borrowing spread do not capture clinical, regulatory, and commercialization risk. Applying the corporate rate would likely overvalue the venture.
Conversely, a diversified industrial company might invest in a long-term contracted infrastructure asset whose cash flows are less volatile than the parent’s. Automatically applying the parent’s higher WACC could reject a value-creating project.
When no close pure-play comparables exist, use scenarios and decision trees rather than hiding all uncertainty in a large discount-rate premium. Cash-flow modeling is often better at representing discrete technical, regulatory, or launch outcomes.
When Not to Use WACC
WACC is not the right discount rate for every asset or capital structure. Use another method when cash flows belong only to equity, debt levels change dramatically and predictably, the tax shield has a distinct risk profile, or the business is a financial institution whose debt functions as an operating input.
Use cost of equity for equity cash flows
Dividend discount models and FCFE models estimate cash flows after debt payments and borrowing. Those flows belong to common shareholders, so discount them at the cost of equity.
Consider APV when debt levels change materially
Adjusted present value separates the value of an all-equity-financed business from financing side effects. It is useful for debt-funded buyouts, project finance, restructurings, or transactions with a scheduled debt paydown because a single constant WACC may not reflect changing debt levels.
Treat banks and insurers differently
For banks, deposits and borrowing are closely tied to operations, regulatory capital matters, and enterprise debt is hard to separate from operating liabilities. Analysts often value equity cash flows directly using the cost of equity or apply sector-specific methods.
Use scenario valuation for binary risk
A higher discount rate is a blunt tool for a drug approval, lawsuit outcome, mineral discovery, or product launch. Probability-weighted scenarios make the event, timing, and payoff visible. Adding an arbitrary premium may obscure rather than measure the risk.
Common WACC Mistakes and How to Fix Them
Most WACC errors come from inconsistent inputs rather than arithmetic. The following checks address the mistakes most likely to change valuation.
| Mistake | Why it is wrong | Better approach |
|---|---|---|
| Using book equity | Historical accounting value does not reflect current investor claims | Use market capitalization or target weights |
| Using coupon rates | Coupons reflect conditions at issuance | Use current yield or marginal borrowing cost |
| Using average tax expense | One-time and deferred items distort the shield | Use an expected marginal rate and test usability |
| Mixing dates | Rates and market values describe different markets | Date every input consistently |
| Mixing currencies | Inflation and sovereign-rate assumptions conflict | Match the rate framework to cash-flow currency |
| Discounting FCFE at WACC | Claimholders do not match | Use cost of equity for FCFE |
| Applying corporate WACC to every project | Project risk may differ | Estimate project-specific risk or scenarios |
| Double counting risk | The same concern reduces cash flow and raises the rate | Map each risk to one primary treatment |
| Ignoring preferred stock or leases | Capital weights and claims are incomplete | Apply a consistent, materiality-based policy |
| Assuming debt is always cheaper | Distress can raise debt cost and equity beta | Re-estimate all components as debt levels change |
| Reporting one precise rate | Inputs are uncertain | Present a range and valuation sensitivity |
| Letting $WACC\le g$ | Perpetual-growth value becomes unstable or invalid | Use economically sustainable growth below WACC |
More debt does not reduce WACC forever
Debt may initially appear cheaper than equity, partly because of seniority and the tax shield. But increasing borrowing raises default risk. Lenders demand a larger spread, equity becomes riskier, beta rises, financial flexibility falls, and expected distress costs grow.
The weighted average can decline over some range and then rise. A spreadsheet that holds the cost of debt and beta constant while increasing borrowing will falsely suggest that the highest possible debt level always creates maximum value.
Historical returns are not automatically required returns
Past stock returns can inform beta, but a company’s realized return over a short period is not its forward-looking cost of equity. A stock that fell 30% last year does not therefore have a negative cost of equity. Required return depends on current risk and market pricing, not a mechanical replay of realized performance.
Tax rates require jurisdiction-level thinking
A consolidated effective tax rate may conceal where debt sits and where taxable income arises. Model a multinational’s interest shield in the entities that incur interest. Consider deduction caps, withholding taxes, transfer-pricing rules, and loss positions when material.
Building WACC in Excel
A transparent WACC worksheet should separate sourced inputs, calculations, outputs, and sensitivities. Hard-coded assumptions need labels, dates, units, and sources. Avoid burying market data inside formulas.
Suggested worksheet layout
| Section | Fields |
|---|---|
| Valuation context | Company, date, currency, cash-flow type, analyst |
| Capital structure | Equity value, debt value, preferred value, weights |
| Cost of equity | Risk-free rate, beta, ERP, additional premiums |
| Cost of debt | Benchmark, spread, yield, marginal tax rate |
| Output | Weighted components, WACC, range |
| Sensitivity | WACC versus terminal growth or exit multiple |
| Sources | URL or document, observation date, notes |
If cells B5 and B6 contain market equity and debt, B8 contains cost of equity, B9 contains pre-tax debt cost, and B10 contains the tax rate, an illustrative Excel expression is:
=(B5/(B5+B6))*B8+(B6/(B5+B6))*B9*(1-B10)Format percentage inputs consistently. Enter 25% as 25% or 0.25, not 25. Add checks that total weights equal 100%, capital values are non-negative, the tax rate lies within a plausible range, and WACC exceeds perpetual growth.
Maintain an audit trail
Each market input should record its source and date. Save the peer list, beta adjustments, debt instruments, tax analysis, and rationale for the target debt level. A reviewer should be able to recreate the rate without guessing what an unlabeled cell means.
Update market-driven inputs at the valuation date and whenever rates, share prices, borrowing, credit quality, or business risk change materially. A quarterly update may suit recurring planning, while a transaction or fairness analysis may require a date-specific refresh.
A Defensible WACC Checklist
Before using the rate, confirm all of the following:
- The valuation date and currency are stated.
- The cash flow is identified as FCFF or FCFE and nominal or real.
- Capital weights use market values or a documented target structure.
- Equity value uses diluted shares consistently with the model.
- Debt includes the instruments treated as financing elsewhere in the valuation.
- The risk-free rate matches currency and has a recorded source date.
- ERP methodology and country-risk treatment are documented.
- Beta reflects comparable operating risk and the intended debt-to-equity ratio.
- Cost of debt reflects current borrowing conditions, not only old coupons.
- The tax shield is based on an appropriate marginal rate and is usable.
- Preferred stock, leases, and hybrids receive consistent treatment.
- Project risk is not assumed equal to corporate risk without review.
- Each major risk is counted once, in cash flow or the rate.
- Sensitivity analysis shows the effect of a reasonable rate range.
- Terminal growth remains below WACC and is economically supportable.
- Sources, judgments, and reviewer checks are preserved.
This checklist is the article’s core practical framework: formula integrity, market evidence, and model consistency. A mathematically correct rate can still be economically wrong if any one of those three fails.
Frequently Asked Questions
Conclusion
The WACC formula is easy to calculate once its inputs are known: weight the cost of equity and the after-tax cost of debt by their shares of market-value capital, then include other material funding sources consistently. The harder work is estimating inputs that describe the same company, risk, date, currency, and cash flow.
For a reliable result, use current market values, a documented CAPM process, a marginal borrowing cost, and a tax shield the company can actually use. Treat leases and hybrid claims consistently, replace company-wide WACC when project risk differs, and show a valuation range instead of pretending the answer is exact.
Northstar’s 7.8% worked result is less important than the method behind it. Define the valuation first, source every input, pass the cash flow-currency-inflation consistency test, and stress-test the rate. That process turns WACC from a compact classroom equation into a defensible decision tool.